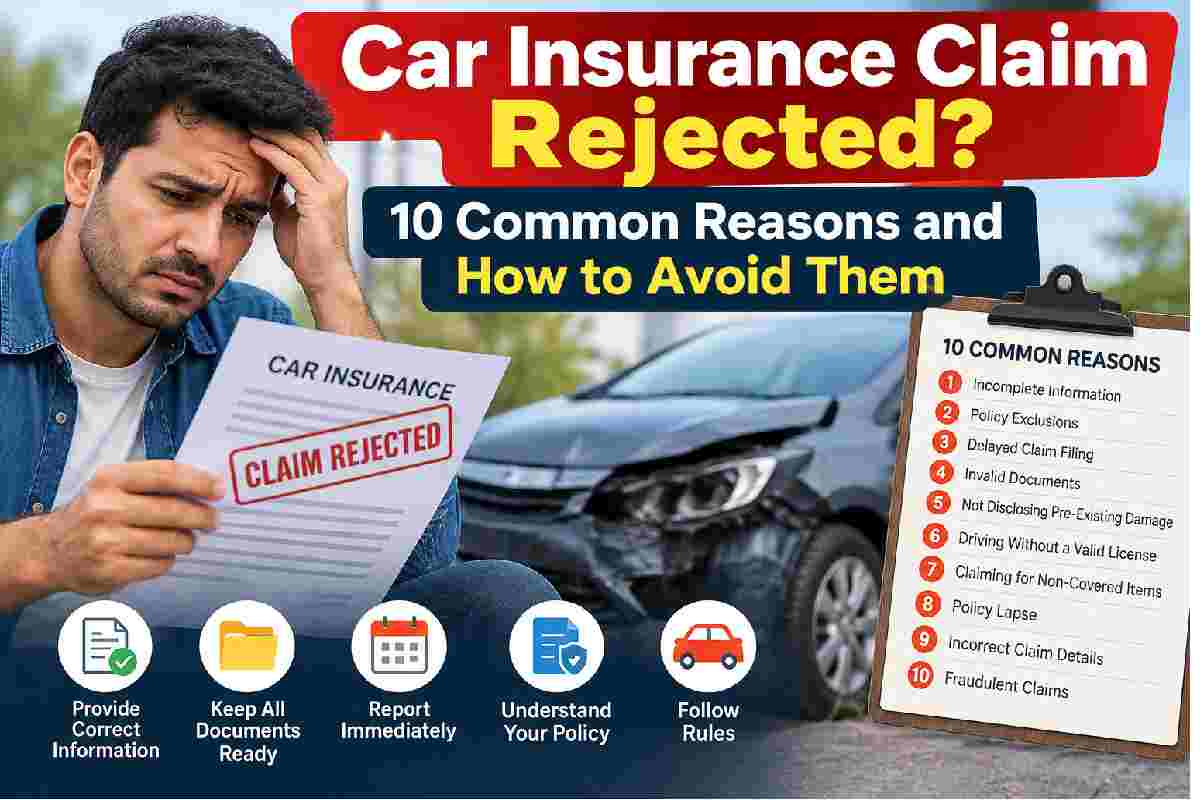
You’ve just been in an accident, and the one thing keeping you sane is knowing your policy has your back. Then the claim comes back rejected. This generally happens more often than most drivers realize, but not because of fraud.
The issue may be quite small: you may have filled out the form incorrectly or forgot to mention a simple detail. Most of these car insurance claim rejections are easy to avoid once you know where they come from. Here’s a breakdown of the ten most common ones, and what to do instead.
Reporting the Accident Too Late
Insurers set a window, usually 24 to 48 hours, for you to report an accident or theft. Miss it, and you’ll have some explaining to do.
Delayed intimation of a car insurance claim makes an insurer wonder what happened in the gap. They may wonder whether the vehicle was tampered with, or the story changed along the way. Call the helpline or open the insurer’s app the moment it happens.
Letting the Policy Lapse
A policy that expired the day before your accident offers exactly zero protection. Renewal dates slip past busy people all the time. If your car insurance policy lapses even briefly and something happens in that window, there’s nothing left to claim against.
Set a reminder two or three weeks ahead of renewal, not the day of, and consider auto-renewal if your insurer offers it so a missed email never turns into a missed payout.
Driving on an Invalid License
Every policy assumes the person behind the wheel is legally allowed to be there. An expired license, a learner’s permit used without a qualified adult beside you, or a license issued for a different vehicle class can all sink a claim instantly.
Check your license’s validity regularly, not just when you happen to remember.
Getting Behind the Wheel Impaired
Claims tied to drunk or drugged driving get rejected almost without exception. It isn’t just the claim at stake either; driving under the influence carries its own legal penalties under the Motor Vehicles Act, independent of what your insurer decides.
There’s no workaround to offer here. If you’ve been drinking, don’t drive at all.
Showing Up Without the Right Paperwork
A car insurance claim usually needs a completed claim form, your registration certificate, a copy of your license, an FIR (where applicable), and repair estimates from the garage.
The process stalls if you forget even a single document. Keep scans of all documents on your phone and a physical folder at home. It takes ten minutes and saves you any confusion later.
Repairing the Car Before It’s Inspected
You may find it tempting to get your car fixed the same day, especially if you need it for work. But you’ve just given the insurer a reason to question what actually happened if a surveyor hasn’t looked at the damage yet.
Wait for the inspection, or take the vehicle to a network garage where the approval process is already built in. Patience here costs a day or two. Skipping it can cost you the whole claim.
Using the Car for Something the Policy Doesn’t Cover
A policy written for personal use doesn’t automatically extend to commercial activity, deliveries, ride-hailing, or ferrying paying passengers.
If your car’s actual use has changed since you bought the policy and you haven’t updated it, an insurer can point to that mismatch and walk away from the claim. It’s worth a five-minute call to your insurer any time how you use the vehicle shifts.
Not Disclosing Modifications or Old Damage
Swapped out the engine, added a body kit, or bought the car with damage you didn’t think worth mentioning?
All of that needs to go on record. Insurers view it as a matter of good faith. Any undisclosed change discovered later can be grounds to deny a claim. Disclose upfront, and it stops being a problem later.
Conflicting Details Between the FIR and the Claim
Authorities notice discrepancies fast if the time, location, or sequence of events in the police report doesn’t match what you’ve told your insurer. It doesn’t have to be intentional, and most people misremember details under stress.
Stick to a clear, consistent account with the police and again with your insurer. Make sure to write down what happened while it’s still fresh.
Not Reading the Exclusions Before You Need Them
Every policy carries a list of exclusions: normal wear and tear, certain types of consequential damage, situations that only add-ons like zero depreciation or engine protection actually cover.
Most people never open that section until they’re filing a claim. That is exactly the wrong moment to discover a gap. Read it when you buy or renew the policy, and ask your agent about anything unclear. That way, you’ll know exactly what’s covered before you need it.
Final Thoughts on Car Insurance Claim Rejections
A rejected claim is almost always related to timing, paperwork, or a detail that you forgot to mention. None of these are hard to get right once you know to look for them.
Report on time, keep your documents in order, and stay within what your policy actually permits. Don’t forget to read the fine print before you’re relying on it. That’s most of what stands between a smooth payout and a frustrating denial.